Independent writing on tax-smart planning, mortgage strategy, and retirement building. For Canadian professionals who want the whole picture, not just a piece of it.
June 2026 Affordability Data Shows Canadian Policymakers Preparing for the Wrong Crisis
A 32-year-old project manager in Burnaby earned $87,000 last year and saved $42,000 for a down payment. She still doesn't qualify for the average condo in her neighborhood. The mortgage stress test requires her to prove she can handle payments at roughly 7.5%, even though her actual rate would be closer to 5.8%. The math doesn't work. It won't work next month either, because the problem isn't the interest rate she'd pay, it's the income threshold she can't clear.
That's the pattern showing up across June 2026 affordability data. Prices climbed another 1.5% to 2% month-over-month in most major markets, inventory stayed below the 10-year seasonal average, and the Bank of Canada held rates essentially flat. The policy conversation remains fixated on when the next rate cut arrives and how much relief it will bring. But rate relief solves a different problem than the one most buyers are facing.
The qualification bar moved faster than wages
The stress test was designed to protect borrowers from payment shock if rates rose after they locked in. It does that job. What it also does, in a market where prices are rising faster than incomes, is create a qualification threshold that moves upward independent of the actual cost of borrowing. In Vancouver, the income required to purchase an average home now sits north of $230,000. That's not an interest rate problem. That's a price-to-income ratio problem, and cutting the overnight rate by 50 basis points doesn't touch it.
When prices rise 18% over 18 months and the median household income rises 3%, the qualification math gets worse even if rates drop slightly. The "affordability crisis" framing assumes the carrying cost is the binding constraint. For a meaningful portion of the market, the binding constraint is clearing the stress test at all. Rate cuts don't fix that. They just make the people who already qualified able to afford slightly more house, which in a supply-constrained market mostly translates to higher bids on the same inventory.
The policy toolbox is aimed at the wrong variable
Every housing announcement out of Ottawa this year has centered on some combination of rate-sensitive stimulus or first-time buyer programs that ease the down payment burden. The Housing Accelerator Fund is delivering units, but not yet at a scale that moves metro-area prices. Meanwhile, the June data shows something uglier: prospective buyers who sat out the spring market hoping for rate cuts lost ground. Prices rose faster than any rate improvement could offset.
The structural issue isn't affordability in the sense of "can you afford the monthly payment." It's qualification in the sense of "does your salary clear the bar the lender is required to enforce." The penalty for missing that bar isn't a higher monthly cost. It's exclusion from the market entirely, which is why the rental spike in Toronto and Vancouver isn't easing, the people who can't qualify aren't disappearing. They're just not buying.
What secondary markets are revealing
Calgary and Edmonton both saw affordability tighten in June, which is unusual for prairie cities that have historically absorbed overflow demand when the big three became unworkable. The "leakage" pattern, buyers priced out of Toronto or Vancouver moving to cheaper metros, has now pushed far enough that the cheaper metros are developing their own qualification problems. That's not an interest rate story. That's a velocity story. Demand moved faster than supply could adjust, and the policy response remains anchored to rate mechanics.
The fix isn't more complex. Build faster, or accept that the market will keep segmenting into a class that qualifies and a class that doesn't, regardless of what the overnight rate does next quarter.

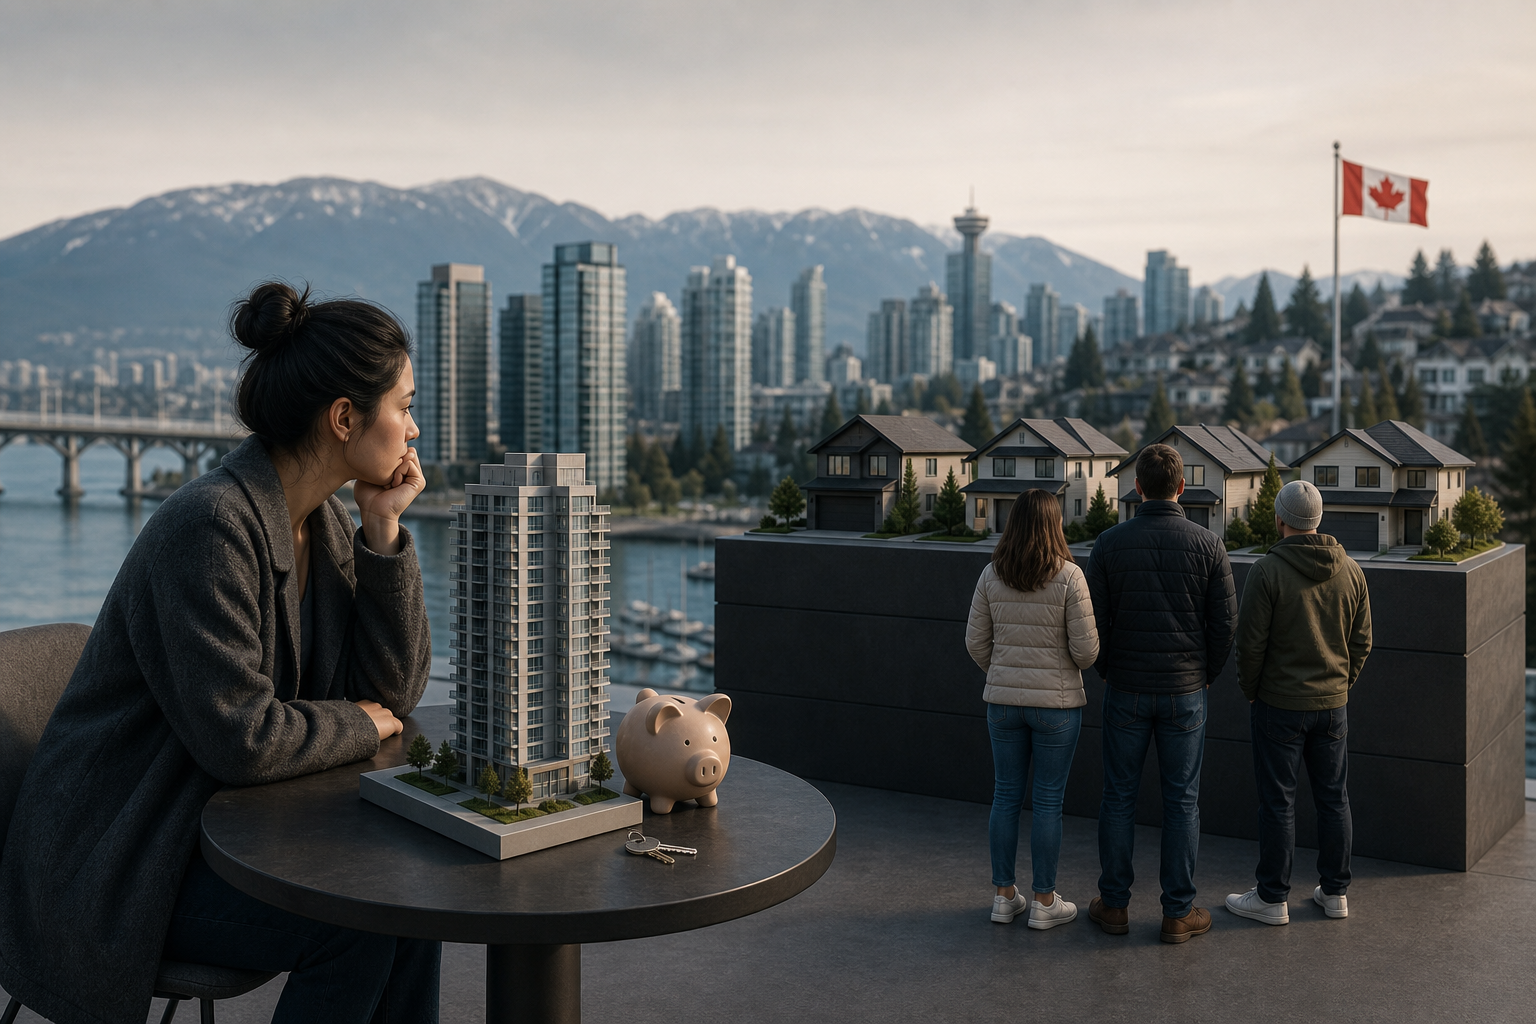

A 32-year-old project manager in Burnaby earned $87,000 last year and saved $42,000 for a down payment. She still doesn't qualify for the average condo in her neighborhood. The mortgage stress test requires her to prove she can handle payments at roughly 7.5%, even though her actual rate would be closer to 5.8%. The math doesn't work. It won't work next month either, because the problem isn't the interest rate she'd pay, it's the income threshold she can't clear.
That's the pattern showing up across June 2026 affordability data. Prices climbed another 1.5% to 2% month-over-month in most major markets, inventory stayed below the 10-year seasonal average, and the Bank of Canada held rates essentially flat. The policy conversation remains fixated on when the next rate cut arrives and how much relief it will bring. But rate relief solves a different problem than the one most buyers are facing.
The qualification bar moved faster than wages
The stress test was designed to protect borrowers from payment shock if rates rose after they locked in. It does that job. What it also does, in a market where prices are rising faster than incomes, is create a qualification threshold that moves upward independent of the actual cost of borrowing. In Vancouver, the income required to purchase an average home now sits north of $230,000. That's not an interest rate problem. That's a price-to-income ratio problem, and cutting the overnight rate by 50 basis points doesn't touch it.
When prices rise 18% over 18 months and the median household income rises 3%, the qualification math gets worse even if rates drop slightly. The "affordability crisis" framing assumes the carrying cost is the binding constraint. For a meaningful portion of the market, the binding constraint is clearing the stress test at all. Rate cuts don't fix that. They just make the people who already qualified able to afford slightly more house, which in a supply-constrained market mostly translates to higher bids on the same inventory.
The policy toolbox is aimed at the wrong variable
Every housing announcement out of Ottawa this year has centered on some combination of rate-sensitive stimulus or first-time buyer programs that ease the down payment burden. The Housing Accelerator Fund is delivering units, but not yet at a scale that moves metro-area prices. Meanwhile, the June data shows something uglier: prospective buyers who sat out the spring market hoping for rate cuts lost ground. Prices rose faster than any rate improvement could offset.
The structural issue isn't affordability in the sense of "can you afford the monthly payment." It's qualification in the sense of "does your salary clear the bar the lender is required to enforce." The penalty for missing that bar isn't a higher monthly cost. It's exclusion from the market entirely, which is why the rental spike in Toronto and Vancouver isn't easing, the people who can't qualify aren't disappearing. They're just not buying.
What secondary markets are revealing
Calgary and Edmonton both saw affordability tighten in June, which is unusual for prairie cities that have historically absorbed overflow demand when the big three became unworkable. The "leakage" pattern, buyers priced out of Toronto or Vancouver moving to cheaper metros, has now pushed far enough that the cheaper metros are developing their own qualification problems. That's not an interest rate story. That's a velocity story. Demand moved faster than supply could adjust, and the policy response remains anchored to rate mechanics.
The fix isn't more complex. Build faster, or accept that the market will keep segmenting into a class that qualifies and a class that doesn't, regardless of what the overnight rate does next quarter.
Read Next
Why DLC paid $58.5 million for Filogix and what brokers actually need to worry about
MCAN's 19% earnings jump proves impaired loans aren't the threat everyone thinks they are
The Personal Letter to Sellers Still Works, Just Not for the Reason You Think
25 States Sue Over Trump Tariffs, Arguing the President Cannot Tax Without Congress