Independent writing on tax-smart planning, mortgage strategy, and retirement building. For Canadian professionals who want the whole picture, not just a piece of it.
CMHC's Latest Forecast Contradicts the Spring Recovery Narrative Most Buyers Are Counting On
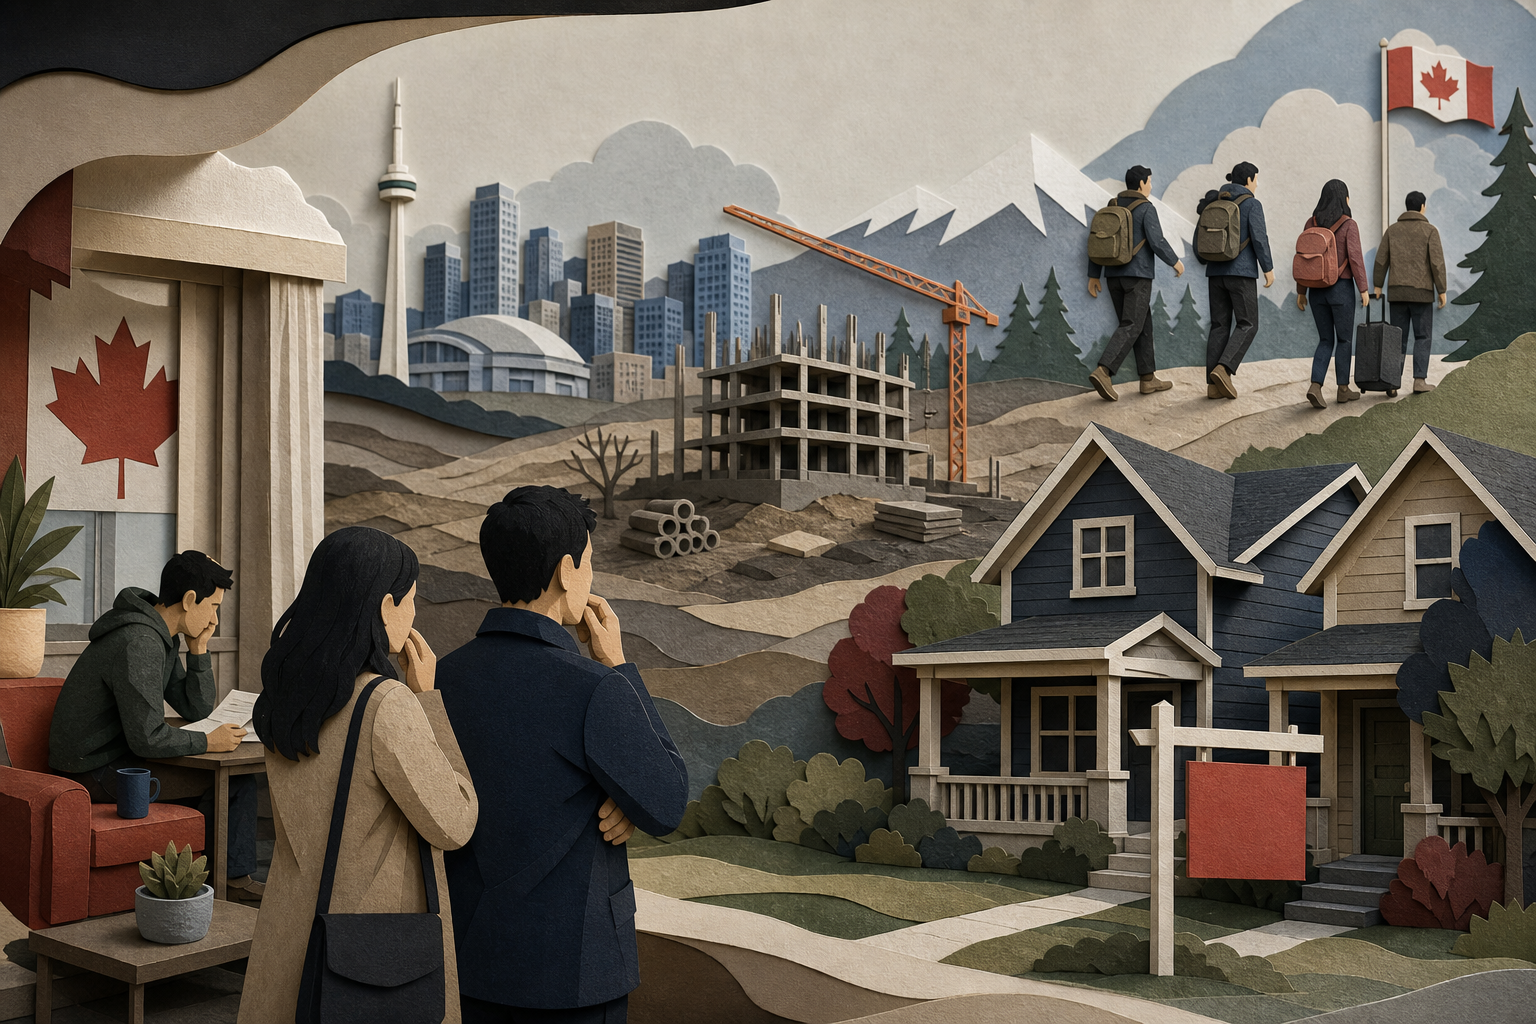
The federal housing agency quietly revised its 2026 outlook last month, projecting that national home prices will fall year-over-year even as mortgage rates tick downward from their peak. That's the opposite of what most first-time buyers have been banking on since last fall.
The logic they've been hearing goes like this: rates have peaked, the Bank of Canada will continue trimming, and by spring 2026 the market will thaw. Listings will climb, competition will ease, but prices will hold or drift gently upward because inventory is still historically tight. Buy in the spring dip, ride the recovery. CMHC's latest Housing Market Outlook doesn't support that sequence. It calls for sales to fall, starts to fall, and prices to follow.
Why the forecast diverges from the recovery story
The typical buyer narrative assumes demand is coiled and waiting. Lower the rate by another 75 basis points and households that have been sitting on the sidelines since 2022 will flood back in. CMHC sees three structural drags that make that flood less likely.
First, borrowing costs are still prohibitively high relative to income. A 5-year fixed rate sitting around 4.5% in early 2026 may be lower than the 2023 peak, but it's double the sub-2% environment that defined 2020 and 2021. Monthly carrying costs on a $600,000 mortgage at 4.5% are roughly $3,400. At 1.8%, they were $2,500. That $900 gap doesn't disappear because rates dropped 100 basis points from the top. For most households, affordability hasn't been restored. It's been degraded slightly less.
Second, population growth is slowing faster than most local markets have priced in. Federal caps on non-permanent residents are designed to bring that cohort down to 5% of the population by 2027. International students and temporary foreign workers have been a meaningful source of rental demand and entry-level purchase activity in Toronto, Vancouver, and Montreal. Removing that inflow doesn't crash the market, but it does flatten the demand curve exactly when builders and sellers are expecting a rebound.
Third, new construction is falling at the worst possible moment. Housing starts are projected to decline in 2026 as developers pull back under the combined weight of high financing costs, labor shortages, and regulatory delays. CMHC estimates Canada needs 3.5 million additional units by 2030 to restore affordability. Losing a year of starts during a supposed recovery phase doesn't just delay that target. It tees up the next supply crunch when rates do eventually normalize and demand returns in force.
What falling starts mean for the buyer who waits
The instinct for most buyers sitting out 2025 is to wait for lower rates and softer prices. If prices do fall modestly in 2026, that instinct will feel validated. But here's the structural problem: every month of suppressed construction during a price decline is a future month of constrained supply once the credit cycle turns. The units that didn't get started in 2026 won't be available in 2028. Prices may soften now and spike later, not because of speculation, but because the physical housing stock fell further behind.
CMHC's outlook also highlights regional divergence. National averages obscure the fact that Alberta, with lower entry prices and stronger interprovincial migration, may hold steadier than Ontario or British Columbia. A buyer in Calgary faces a different 2026 than a buyer in Mississauga. Treating the spring market as a uniform national event leads to timing errors.
The recovery narrative isn't fiction. It's just scheduled for a later act than most buyers assume. The question isn't whether affordability improves. It's whether it improves before the structural supply deficit turns a modest dip into the setup for the next run.


The federal housing agency quietly revised its 2026 outlook last month, projecting that national home prices will fall year-over-year even as mortgage rates tick downward from their peak. That's the opposite of what most first-time buyers have been banking on since last fall.
The logic they've been hearing goes like this: rates have peaked, the Bank of Canada will continue trimming, and by spring 2026 the market will thaw. Listings will climb, competition will ease, but prices will hold or drift gently upward because inventory is still historically tight. Buy in the spring dip, ride the recovery. CMHC's latest Housing Market Outlook doesn't support that sequence. It calls for sales to fall, starts to fall, and prices to follow.
Why the forecast diverges from the recovery story
The typical buyer narrative assumes demand is coiled and waiting. Lower the rate by another 75 basis points and households that have been sitting on the sidelines since 2022 will flood back in. CMHC sees three structural drags that make that flood less likely.
First, borrowing costs are still prohibitively high relative to income. A 5-year fixed rate sitting around 4.5% in early 2026 may be lower than the 2023 peak, but it's double the sub-2% environment that defined 2020 and 2021. Monthly carrying costs on a $600,000 mortgage at 4.5% are roughly $3,400. At 1.8%, they were $2,500. That $900 gap doesn't disappear because rates dropped 100 basis points from the top. For most households, affordability hasn't been restored. It's been degraded slightly less.
Second, population growth is slowing faster than most local markets have priced in. Federal caps on non-permanent residents are designed to bring that cohort down to 5% of the population by 2027. International students and temporary foreign workers have been a meaningful source of rental demand and entry-level purchase activity in Toronto, Vancouver, and Montreal. Removing that inflow doesn't crash the market, but it does flatten the demand curve exactly when builders and sellers are expecting a rebound.
Third, new construction is falling at the worst possible moment. Housing starts are projected to decline in 2026 as developers pull back under the combined weight of high financing costs, labor shortages, and regulatory delays. CMHC estimates Canada needs 3.5 million additional units by 2030 to restore affordability. Losing a year of starts during a supposed recovery phase doesn't just delay that target. It tees up the next supply crunch when rates do eventually normalize and demand returns in force.
What falling starts mean for the buyer who waits
The instinct for most buyers sitting out 2025 is to wait for lower rates and softer prices. If prices do fall modestly in 2026, that instinct will feel validated. But here's the structural problem: every month of suppressed construction during a price decline is a future month of constrained supply once the credit cycle turns. The units that didn't get started in 2026 won't be available in 2028. Prices may soften now and spike later, not because of speculation, but because the physical housing stock fell further behind.
CMHC's outlook also highlights regional divergence. National averages obscure the fact that Alberta, with lower entry prices and stronger interprovincial migration, may hold steadier than Ontario or British Columbia. A buyer in Calgary faces a different 2026 than a buyer in Mississauga. Treating the spring market as a uniform national event leads to timing errors.
The recovery narrative isn't fiction. It's just scheduled for a later act than most buyers assume. The question isn't whether affordability improves. It's whether it improves before the structural supply deficit turns a modest dip into the setup for the next run.
Read Next
Why DLC paid $58.5 million for Filogix and what brokers actually need to worry about
MCAN's 19% earnings jump proves impaired loans aren't the threat everyone thinks they are
The Personal Letter to Sellers Still Works, Just Not for the Reason You Think
25 States Sue Over Trump Tariffs, Arguing the President Cannot Tax Without Congress