Independent writing on tax-smart planning, mortgage strategy, and retirement building. For Canadian professionals who want the whole picture, not just a piece of it.
CMHC Cuts Housing Starts Forecast by 20%: What the Agency's Reversal Means for Development Capital
The agency's internal models now show annual housing starts falling to 195,000 units by late 2026, down from earlier projections that hovered near 240,000. That's a gap of 45,000 homes per year that won't break ground, and it's happening at the same time the federal government is telling cities it needs 3.87 million new units built by 2031 to close the affordability gap. The arithmetic doesn't work.
Why the forecast collapsed
Three variables moved at once. First, the U.S. tariff fight on softwood lumber escalated in early 2025, pushing framing costs up 18-22% depending on the region. Developers who penciled projects at $180 per square foot are now looking at $215, and the pro forma math that worked six months ago doesn't clear the hurdle rate anymore. Second, Toronto and Vancouver are sitting on roughly 9,200 unsold condo units, most of them completed towers that investors walked away from when carrying costs started exceeding potential rental income. Builders can't get construction financing without 70-80% pre-sales, and investors aren't signing. Third, Ottawa capped non-permanent residents, international students, temporary workers, with the goal of reducing their share of the population to 5% by late 2026. That's roughly 400,000 fewer people competing for rentals in the next 24 months, which removes the demand spike that was propping up speculative builds.
CMHC didn't predict these variables independently. It responded to them after they showed up in permit data, which means the forecast is already baked into what's happening on the ground.
The lag problem developers face
Housing starts are a trailing indicator dressed up as a leading one. A "start" gets counted when the foundation is poured, but the capital decision happened 18-36 months earlier. What we're seeing now in the data is the result of decisions made in 2022 and early 2023, when the Bank of Canada was still at 0.25% and pre-construction deposits were flowing. The current freeze, where starts are forecast to drop, reflects decisions being made right now, in an environment where the policy rate sits at 4.5%, construction loans are priced north of 7%, and the buyer base has evaporated.
The dangerous part is the mirror image on the back end. Projects started in 2021-2022 are completing now, which is why inventory is spiking even as new starts collapse. We're living through high supply and collapsing future supply at the same time. By 2027, completions will fall off a cliff because nothing is starting today. The gap between completions and household formation will widen, not narrow, unless something breaks the capital logjam in the next 12 months.
Where the money is actually flowing
The one segment still moving is purpose-built rental. The 100% GST rebate on new rental construction, implemented in late 2023, is the only policy lever strong enough to offset the interest rate environment. Developers who can't make condo projects pencil are pivoting to rental towers because the rebate saves them $40,000-$60,000 per unit, and institutional capital (pension funds, REITs) is still willing to finance rental at scale. But rental doesn't solve the ownership supply problem, and the rebate expires in 2031. What happens after that is an open question no one at CMHC is answering yet.
The forecast revision isn't a prediction. It's confirmation that the capital required to hit federal housing targets doesn't exist at current prices.

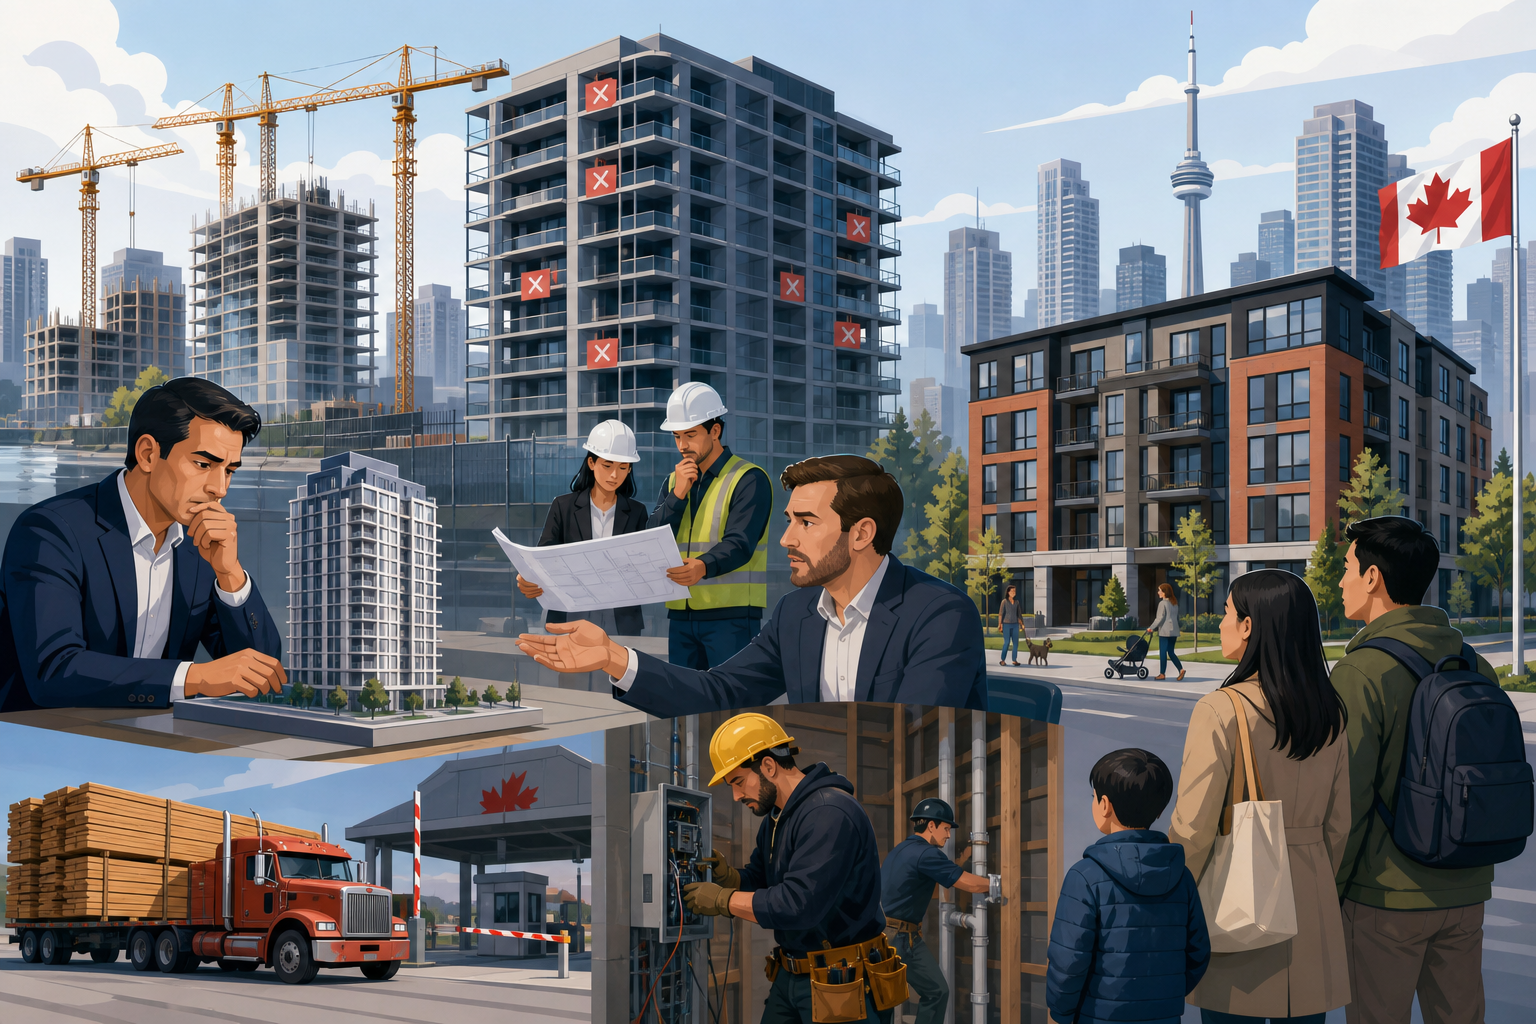

The agency's internal models now show annual housing starts falling to 195,000 units by late 2026, down from earlier projections that hovered near 240,000. That's a gap of 45,000 homes per year that won't break ground, and it's happening at the same time the federal government is telling cities it needs 3.87 million new units built by 2031 to close the affordability gap. The arithmetic doesn't work.
Why the forecast collapsed
Three variables moved at once. First, the U.S. tariff fight on softwood lumber escalated in early 2025, pushing framing costs up 18-22% depending on the region. Developers who penciled projects at $180 per square foot are now looking at $215, and the pro forma math that worked six months ago doesn't clear the hurdle rate anymore. Second, Toronto and Vancouver are sitting on roughly 9,200 unsold condo units, most of them completed towers that investors walked away from when carrying costs started exceeding potential rental income. Builders can't get construction financing without 70-80% pre-sales, and investors aren't signing. Third, Ottawa capped non-permanent residents, international students, temporary workers, with the goal of reducing their share of the population to 5% by late 2026. That's roughly 400,000 fewer people competing for rentals in the next 24 months, which removes the demand spike that was propping up speculative builds.
CMHC didn't predict these variables independently. It responded to them after they showed up in permit data, which means the forecast is already baked into what's happening on the ground.
The lag problem developers face
Housing starts are a trailing indicator dressed up as a leading one. A "start" gets counted when the foundation is poured, but the capital decision happened 18-36 months earlier. What we're seeing now in the data is the result of decisions made in 2022 and early 2023, when the Bank of Canada was still at 0.25% and pre-construction deposits were flowing. The current freeze, where starts are forecast to drop, reflects decisions being made right now, in an environment where the policy rate sits at 4.5%, construction loans are priced north of 7%, and the buyer base has evaporated.
The dangerous part is the mirror image on the back end. Projects started in 2021-2022 are completing now, which is why inventory is spiking even as new starts collapse. We're living through high supply and collapsing future supply at the same time. By 2027, completions will fall off a cliff because nothing is starting today. The gap between completions and household formation will widen, not narrow, unless something breaks the capital logjam in the next 12 months.
Where the money is actually flowing
The one segment still moving is purpose-built rental. The 100% GST rebate on new rental construction, implemented in late 2023, is the only policy lever strong enough to offset the interest rate environment. Developers who can't make condo projects pencil are pivoting to rental towers because the rebate saves them $40,000-$60,000 per unit, and institutional capital (pension funds, REITs) is still willing to finance rental at scale. But rental doesn't solve the ownership supply problem, and the rebate expires in 2031. What happens after that is an open question no one at CMHC is answering yet.
The forecast revision isn't a prediction. It's confirmation that the capital required to hit federal housing targets doesn't exist at current prices.
Read Next
Why DLC paid $58.5 million for Filogix and what brokers actually need to worry about
MCAN's 19% earnings jump proves impaired loans aren't the threat everyone thinks they are
The Personal Letter to Sellers Still Works, Just Not for the Reason You Think
25 States Sue Over Trump Tariffs, Arguing the President Cannot Tax Without Congress