Independent writing on tax-smart planning, mortgage strategy, and retirement building. For Canadian professionals who want the whole picture, not just a piece of it.
30 Ontario Investors Lost $5.3 Million to a MIC That Never Invested Their Money
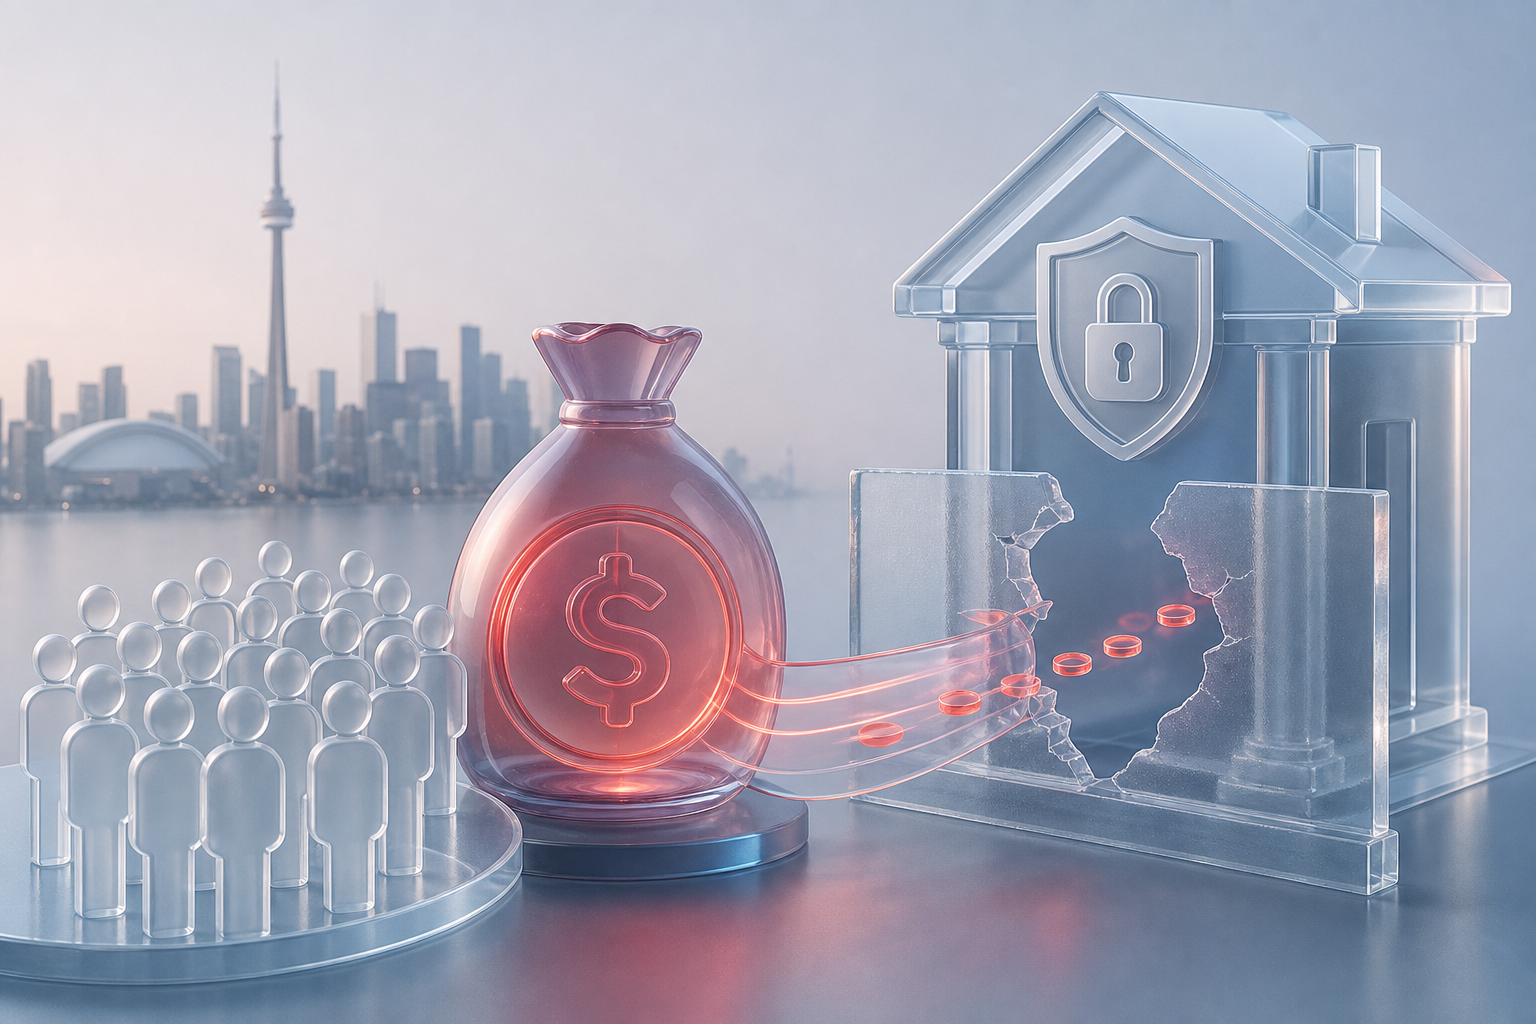
The former operator of Altmore Mortgage Investment Corporation stood in a Toronto courtroom last month and pleaded guilty to charges brought by the Ontario Securities Commission. The money his investors believed was secured by real estate mortgages had, in fact, never been invested in mortgages at all.
The scheme ran for years. Investors, most of them living in the GTA, put money into what they understood to be a standard MIC structure: pooled capital, diversified across multiple mortgage loans, each loan secured by a property. The pitch emphasized security. The word "mortgage" was in the company name. The returns were described as consistent, competitive with the private lending market, and taxed as interest income rather than dividends, which made them particularly attractive in registered accounts like RRSPs.
The problem was the mortgages didn't exist.
What the investors thought they were buying
A legitimate MIC operates under a relatively clear framework in Ontario. It pools capital from investors, lends that capital to borrowers who can't or won't access traditional bank financing, and secures each loan with a registered charge against the borrower's property. The investor receives a share of the interest income, proportional to the capital they contributed. The structure exists to serve two groups: homeowners who need liquidity outside the Big Six banks, and investors who want real estate exposure without the operational burden of being a landlord.
Altmore presented itself as exactly that structure. The company solicited funds under the premise that each dollar would flow into a diversified pool of real estate-secured loans. Investors received statements showing portfolio performance. The language matched what a working MIC would produce.
The Ontario Securities Commission's investigation, which began after a routine compliance review flagged accounting anomalies, revealed that the capital was being diverted. The specifics of where the $5.3 million went will likely emerge during sentencing, but the pattern is familiar: operating expenses, personal withdrawals, payments to earlier investors to sustain the appearance of returns. Classic Ponzi mechanics dressed in the language of mortgage underwriting.
The word "secured" doing heavy lifting
The psychological appeal of a MIC, particularly to conservative investors, rests on one word: secured. If the loan is secured by a property, the thinking goes, the principal is protected. Even if the borrower defaults, the lender forecloses and recovers the capital through the sale of the asset.
That logic holds only if the underlying loan exists and the security is properly registered. In Altmore's case, neither condition was met. The security was a fiction. The investors were unsecured creditors from the start, which is the worst position to hold when a scheme collapses.
The problem is that verifying the existence and quality of mortgage assets is not straightforward for a retail investor. A legitimate MIC will provide annual audited financials, but those financials rely on the accuracy of the company's own records. If the operator is fabricating loan documents, the auditor is working from false inputs. The investor, unless they personally pull title on every property in the portfolio, has no way to independently confirm that the mortgages are real.
What happens now
A guilty plea is a legal milestone, not a financial one. The investors are unlikely to recover most of their capital. The funds are spent. The operator may face restitution orders and jail time, but neither brings back five million dollars that no longer exists in a recoverable form.
The case will likely accelerate enforcement scrutiny of other MICs operating in the exempt market, which is the regulatory category where most private lending funds sit. These products are sold without a prospectus, which means they bypass the disclosure requirements that apply to publicly traded securities. The trade-off is supposed to be investor sophistication, but sophistication doesn't help when the documents are forged.
Altmore's closure damages the credibility of legitimate private lenders in Ontario, who now operate under the shadow of a scheme that used their industry's language to commit fraud.


The former operator of Altmore Mortgage Investment Corporation stood in a Toronto courtroom last month and pleaded guilty to charges brought by the Ontario Securities Commission. The money his investors believed was secured by real estate mortgages had, in fact, never been invested in mortgages at all.
The scheme ran for years. Investors, most of them living in the GTA, put money into what they understood to be a standard MIC structure: pooled capital, diversified across multiple mortgage loans, each loan secured by a property. The pitch emphasized security. The word "mortgage" was in the company name. The returns were described as consistent, competitive with the private lending market, and taxed as interest income rather than dividends, which made them particularly attractive in registered accounts like RRSPs.
The problem was the mortgages didn't exist.
What the investors thought they were buying
A legitimate MIC operates under a relatively clear framework in Ontario. It pools capital from investors, lends that capital to borrowers who can't or won't access traditional bank financing, and secures each loan with a registered charge against the borrower's property. The investor receives a share of the interest income, proportional to the capital they contributed. The structure exists to serve two groups: homeowners who need liquidity outside the Big Six banks, and investors who want real estate exposure without the operational burden of being a landlord.
Altmore presented itself as exactly that structure. The company solicited funds under the premise that each dollar would flow into a diversified pool of real estate-secured loans. Investors received statements showing portfolio performance. The language matched what a working MIC would produce.
The Ontario Securities Commission's investigation, which began after a routine compliance review flagged accounting anomalies, revealed that the capital was being diverted. The specifics of where the $5.3 million went will likely emerge during sentencing, but the pattern is familiar: operating expenses, personal withdrawals, payments to earlier investors to sustain the appearance of returns. Classic Ponzi mechanics dressed in the language of mortgage underwriting.
The word "secured" doing heavy lifting
The psychological appeal of a MIC, particularly to conservative investors, rests on one word: secured. If the loan is secured by a property, the thinking goes, the principal is protected. Even if the borrower defaults, the lender forecloses and recovers the capital through the sale of the asset.
That logic holds only if the underlying loan exists and the security is properly registered. In Altmore's case, neither condition was met. The security was a fiction. The investors were unsecured creditors from the start, which is the worst position to hold when a scheme collapses.
The problem is that verifying the existence and quality of mortgage assets is not straightforward for a retail investor. A legitimate MIC will provide annual audited financials, but those financials rely on the accuracy of the company's own records. If the operator is fabricating loan documents, the auditor is working from false inputs. The investor, unless they personally pull title on every property in the portfolio, has no way to independently confirm that the mortgages are real.
What happens now
A guilty plea is a legal milestone, not a financial one. The investors are unlikely to recover most of their capital. The funds are spent. The operator may face restitution orders and jail time, but neither brings back five million dollars that no longer exists in a recoverable form.
The case will likely accelerate enforcement scrutiny of other MICs operating in the exempt market, which is the regulatory category where most private lending funds sit. These products are sold without a prospectus, which means they bypass the disclosure requirements that apply to publicly traded securities. The trade-off is supposed to be investor sophistication, but sophistication doesn't help when the documents are forged.
Altmore's closure damages the credibility of legitimate private lenders in Ontario, who now operate under the shadow of a scheme that used their industry's language to commit fraud.
Read Next
Why DLC paid $58.5 million for Filogix and what brokers actually need to worry about
MCAN's 19% earnings jump proves impaired loans aren't the threat everyone thinks they are
The Personal Letter to Sellers Still Works, Just Not for the Reason You Think
25 States Sue Over Trump Tariffs, Arguing the President Cannot Tax Without Congress